China’s central bank will raise the foreign-exchange deposit reserve ratio for financial institutions to 6% from 4%, effective from 15 November, the People’s Bank of China (PBOC) said on Tuesday.
The decision, reported by Reuters, is aimed at strengthening the management of foreign-exchange liquidity in financial institutions, according to the central bank. The PBOC did not, in the announcement as reported, set out the size of the foreign-exchange deposits that will be affected, nor did it say it was targeting a particular level for the yuan.
The ratio sets the share of banks’ foreign-currency deposits that must be held as reserves at the central bank. Raising it therefore parks a larger proportion of that foreign currency at the PBOC, leaving less of it in banks’ hands to lend or deploy in the market. Cutting the ratio does the reverse, releasing foreign-currency liquidity. The tool is thus one way for the central bank to influence the supply and demand balance in the foreign-exchange market, rather than a change to interest rates or to the amount of yuan in circulation.
The timing is notable. The yuan has been trading near its strongest level against the dollar in more than four years, at around 6.65 yuan per dollar in recent sessions, after gaining roughly 5% during 2026. On Monday, the PBOC set its daily yuan reference rate at 6.7146 per dollar, weaker than market participants had expected, a gap that market watchers read as a sign the central bank wanted to slow the pace of the currency’s rise rather than encourage a rapid rally.
That reading is interpretation, not something the PBOC stated in Tuesday’s announcement. The bank’s own stated reason was the management of foreign-exchange liquidity, and no analyst reaction or market response was included in the initial Reuters report. Readers should therefore treat any claim about the move’s precise motive for the yuan as provisional until the PBOC or fuller market reporting says more.
The step is the second change to China’s monetary framework in as many days, but it is a different tool from Monday’s move. On Monday, the PBOC formally shifted its main policy rate to an overnight lending rate, injecting 541 billion yuan into the banking system through overnight reverse repurchase agreements priced at 1.25%. Tuesday’s change, by contrast, concerns how much foreign currency banks must keep on reserve, and it takes effect later, on 15 November, giving institutions time to adjust their positions.
What happens next will depend on how banks respond and on whether the PBOC follows up with further guidance. A higher reserve ratio tightens foreign-currency liquidity at the margin, but it does not by itself set the exchange rate, which in China is managed around a daily reference rate with a trading band. Markets will watch the PBOC’s daily fixings, the yuan’s movement towards 15 November, and any further statements from the bank for clues about how forcefully it intends to manage the currency’s recent strength.
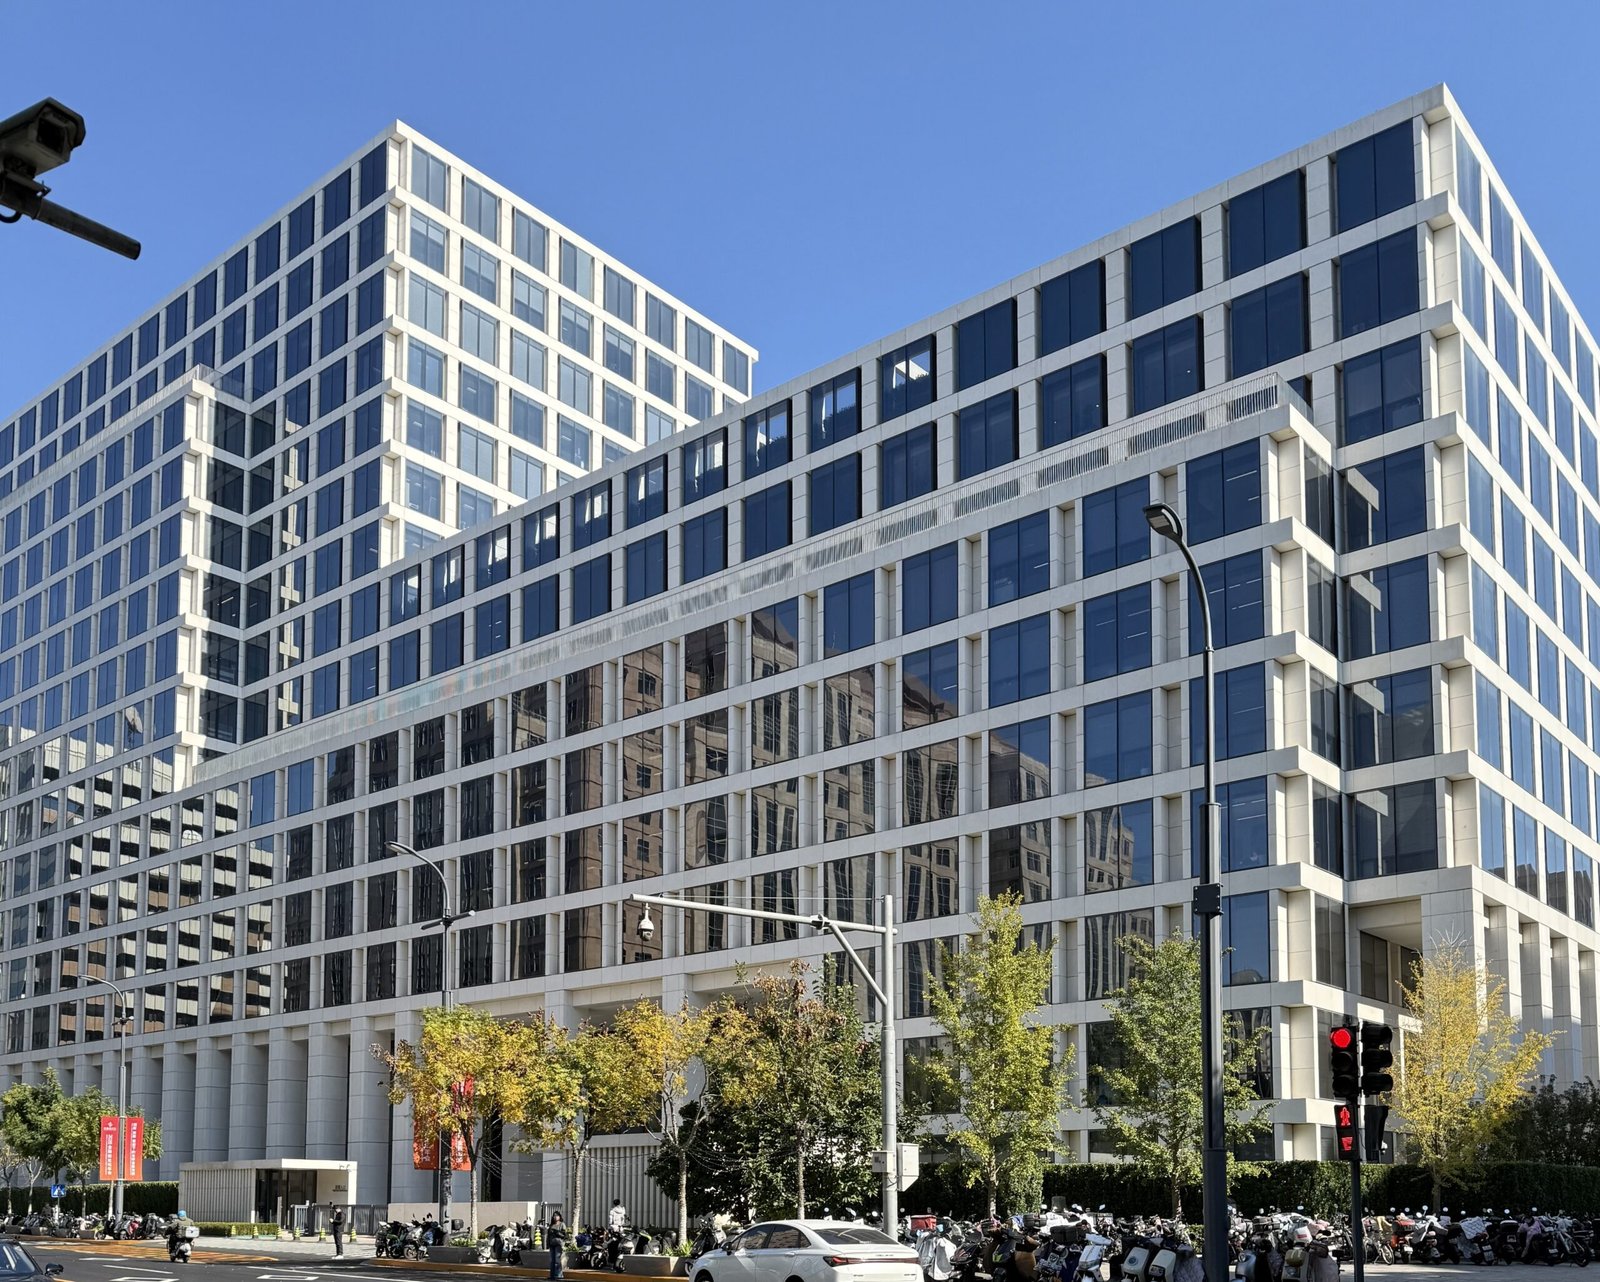
Note: the featured image is a file photo of the People’s Bank of China headquarters in Beijing, not a photograph taken on the day of the announcement.
Sources: Reuters, “China to raise forex deposit reserve ratio to 6% starting November 15“, 3 November 2026, https://www.reuters.com/world/asia-pacific/china-raise-forex-deposit-reserve-ratio-6-starting-november-15-2026-11-03/ ; TradingView News, “Offshore Yuan Rallies to Over 4-Year High“, 2 November 2026, https://www.tradingview.com/news/te_news:597106:0-offshore-yuan-rallies-to-over-4-year-high/