Asian share markets slipped on Monday as unease about the sustainability of the artificial intelligence investment boom continued to hang over technology stocks, while the high price of oil limited the appeal of government bonds as a refuge.
Japan’s Nikkei fell 0.5% and South Korea’s benchmark lost 0.8%, having already shed 16% last month. The broader MSCI index of Asia-Pacific shares outside Japan eased 0.4%. In Europe, futures pointed to a steadier open, with EUROSTOXX 50 futures up 0.1% and DAX futures flat, while S&P 500 futures edged up 0.4% and Nasdaq futures rose 0.6%.
The caution follows a bruising October for technology shares. The Nasdaq lost almost 7% over the month, its worst performance since the tariff rout of April 2025, after investors began to question whether the enormous sums being poured into AI infrastructure will generate returns quickly enough. That doubt has spread beyond equities: the cost of insuring against corporate defaults rose sharply last week, amid concerns about negative cash flow and the sheer scale of AI capital spending.
Gold, often sold by stressed investors to raise cash for margin calls, hit a one-year low before recovering 0.6% to $3,898 an ounce, after falling 6.8% last month. Oil slipped as Iranian and Qatari officials held a third straight day of talks aimed at ending the US-Israeli war on Iran: Brent futures fell 1.5% to $111.72 a barrel, after jumping 13.6% in October, while US crude eased 1.7% to $102.37.
Goldman Sachs analysts expect capital spending by the large cloud and AI companies known as hyperscalers to almost double to $800 billion this year, rising further to $1.2 trillion in 2027. At the same time, they expect earnings growth across the S&P 500 of nearly 30% in 2026, slowing to 18% next year. In a note, Goldman’s chief US equity strategist Ben Snider argued that earnings growth is strong but no longer accelerating, and that growth in AI capital spending is peaking even as spending itself keeps rising.
That makes this week’s earnings season a test. Apple, AMD and Palantir are all due to report, in the wake of Intel’s near-29% tumble on Friday. Investors will be watching for evidence that AI demand is translating into profits, rather than simply into ever-larger investment plans.
Politics adds another wrinkle. In the United States, midterm elections this week could, if Democrats win either or both houses, create further hurdles for data centres. Withdrawals from Binance also unsettled sentiment, after the world’s largest cryptocurrency exchange returned online on Sunday following the theft of billions of dollars from the platform last week.
Bond markets offered only a partial reprieve. Yields on 10-year US Treasuries nudged up to 4.952%, still well below their October peak of 5.3645%, while two-year yields stood at 4.612%. Futures still imply a 72% chance of a quarter-point Federal Reserve rate rise in December, but only 55 basis points of total tightening are now priced in, down from more than 70 basis points a month ago, as investors wonder whether a sustained equity sell-off could deter the Fed from hiking.
Central banks meeting this week include the Reserve Bank of Australia, the Bank of England and Sweden’s Riksbank, where markets are wagering on rate rises, while Norway’s Norges Bank is expected to hold. On the data front, the influential US ISM manufacturing survey for October is due later on Monday, and Friday brings the payrolls report, with median forecasts for a 65,000 rise in jobs after September’s disappointing 29,000 gain, and unemployment holding at 4.2%.
In currencies, the euro was flat at $1.1156 and the dollar barely changed at 157.62 yen, with most of the action concentrated in stocks. For now, the market’s message is one of patience wearing thin: the AI boom is not being written off, but investors want proof that the spending will pay.
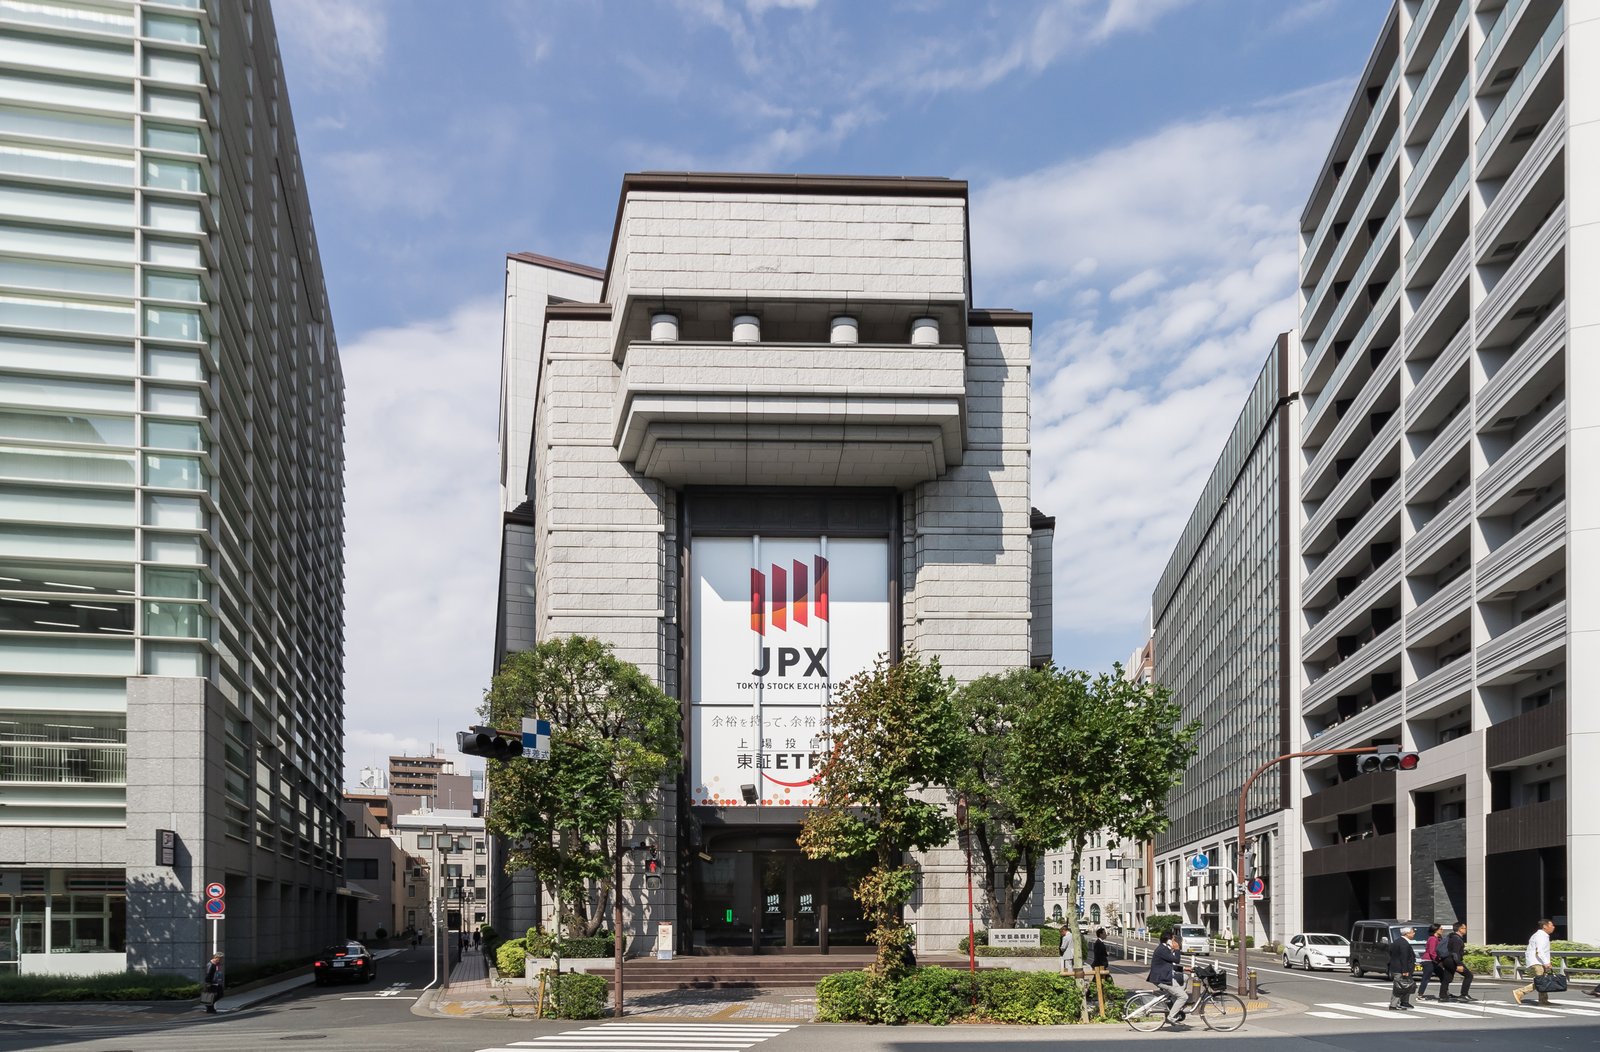
Note: the featured image is a file photo of the Tokyo Stock Exchange building from October 2018, not a photograph of Monday’s trading.
Sources: Reuters, “Asia shares bend under AI stress; Apple earnings loom”, 2 November 2026, https://www.reuters.com/world/china/global-markets-global-markets-2026-11-02/